🏆 Royal Premier Club Award 2025/2026 | 📞 647-492-6189 | www.teamprestige.caTeam PrestigeHarleen Singh & Priya Gill · Royal Canadian RealtyRoyal Premier Club

Dated: June 17 2026
Views: 184
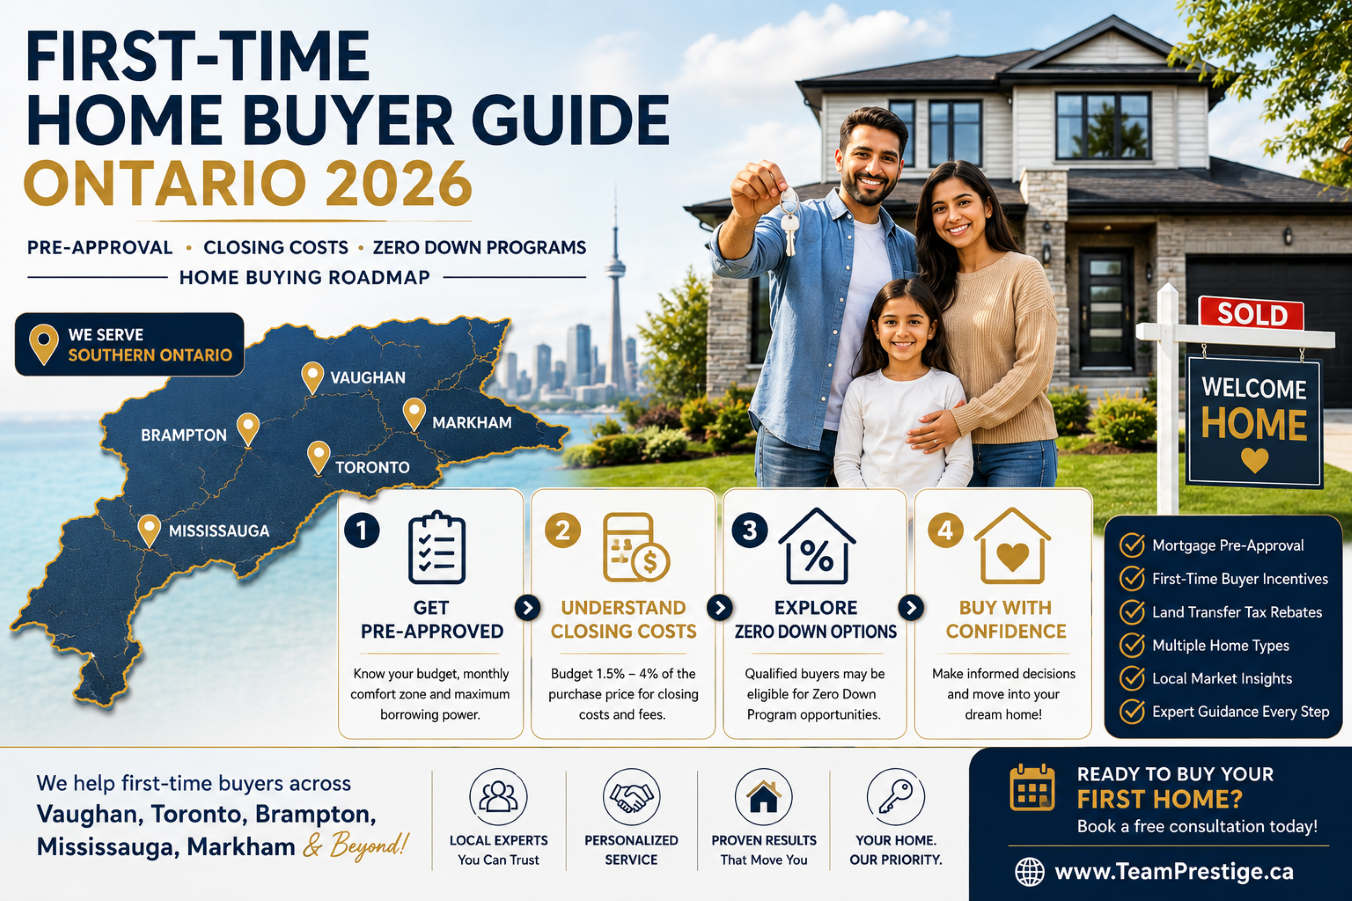
Buying your first home in Southern Ontario doesn't have to be overwhelming. This guide walks you through every step — from getting pre-approved to understanding what you'll pay at closing — including how the Zero Down Program may help you buy sooner than you think.
Buying your first home in Southern Ontario can feel overwhelming, but it becomes much more manageable when you understand the sequence, the costs, and the financing options available to you. Whether you're eyeing a townhouse in Vaughan, a condo in Mississauga, or a detached home in Brampton, the fundamentals are the same — and the right guidance makes all the difference.
One option that many qualified first-time buyers overlook is the Zero Down Program, which is designed to help buyers reduce the upfront cash needed to enter the market. We'll cover that in detail — but first, let's walk through the entire home buying journey.
Know your budget, monthly comfort zone, and maximum borrowing power before you start searching.
Budget 1.5%–4% of the purchase price for closing costs and fees beyond your down payment.
Qualified buyers may be eligible for Zero Down Program opportunities to preserve their cash.
Make informed decisions with expert guidance and move into your dream home with peace of mind.
The process always starts with clarity: knowing your budget, your monthly comfort zone, and the type of home you're looking for. In Canada, mortgage lenders examine your income, debts, savings, and credit profile before approving financing. You'll also need to pass the mortgage stress test, which qualifies you at a rate higher than your actual contract rate — this ensures you can handle potential future rate increases.
Once you've secured pre-approval, you can search for homes, compare neighbourhoods, and evaluate total cost of ownership — not just the purchase price. This matters especially in markets like Vaughan, Brampton, and Mississauga, where monthly carrying costs, property taxes, and closing costs can significantly shift what feels affordable.
Pre-approval is far more than a rough estimate — it's a structured review of your full financial picture. Lenders will typically ask for:
If your credit history is thin or has past challenges, you may need to rebuild your score or pay down existing debts before qualifying for the best mortgage terms. The good news: getting pre-approved early gives you the time to address these factors before you're ready to make an offer.
A strong pre-approval also makes you a more competitive buyer. Sellers — especially in active GTA neighbourhoods — view pre-approved buyers as serious. It protects you from shopping for homes outside your real budget and reduces the chance of costly surprises after your offer is accepted.
One of the biggest mistakes first-time buyers make is focusing only on the down payment. In Ontario, you should budget an additional 1.5% to 4% of the home's purchase price for closing costs. Here's what that typically includes:
| Cost Item | Estimated Range | Notes |
|---|---|---|
| Land Transfer Tax (Ontario) | Tiered by price | Calculated using a provincial tiered formula |
| Legal Fees (Real Estate Lawyer) | $1,500 – $2,500+ | Handles title transfer and closing paperwork |
| Title Insurance | $250 – $500+ | Often required by lenders |
| Home Inspection Fee | $400 – $700 | Optional but strongly recommended |
| Appraisal Fee | $300 – $600 | May be required by lender to confirm value |
| Toronto Municipal LTT | Additional cost | Toronto buyers only — first-time buyer rebates may apply |
| Total Closing Budget | 1.5% – 4% of purchase price | Budget on the higher end to avoid surprises |
For buyers in the City of Toronto, the additional municipal land transfer tax is a real cost — but first-time buyers may qualify for rebates that reduce the burden considerably. Ontario's provincial land transfer tax also has a first-time buyer rebate program. If you're purchasing a new construction home, GST/HST rebates may also apply depending on the price and property type.
For qualified first-time buyers who are financially stable but haven't yet saved a full traditional down payment, the Zero Down Program offers a path to homeownership sooner. Team Prestige has helped buyers across the GTA use this program to preserve their cash for renovations, investments, or other financial priorities.
Minimum 650+ credit score required to qualify
Stable employment history of at least 2 years
2% of purchase price available for closing costs
Canadian citizen or permanent resident
The home price you qualify for under the Zero Down Program depends on your gross family income and credit profile. A personalized consultation with our team will help you understand exactly what you can qualify for based on your unique situation.
The biggest advantage of this program is timing. If you're financially ready — steady income, solid credit, manageable debts — but cash-light, the right plan can move you from renting to owning years ahead of when you might have otherwise expected.
Southern Ontario is not a one-size-fits-all market. Vaughan, Mississauga, Toronto, Markham, Oakville, and Brampton each have different pricing dynamics, tax implications, school district considerations, and buyer competition levels. Local guidance isn't a luxury — it's how you avoid costly mistakes.
A knowledgeable agent can help you determine:
These aren't questions you want to answer alone. The right advice at the right moment can save you tens of thousands of dollars and months of stress. That's exactly what Team Prestige delivers across every market we serve.
❓ What is the Zero Down Program for first-time home buyers in Ontario?
The Zero Down Program helps qualified first-time buyers reduce the upfront savings needed to enter the market. To be eligible, buyers typically need a minimum credit score of 650+, stable employment for two years, 2% of the purchase price available for closing costs, and must be a Canadian citizen or permanent resident. The qualifying home price is determined by gross family income and credit profile.
❓ How much are closing costs when buying a home in Ontario?
Ontario buyers should budget 1.5% to 4% of the home's purchase price for closing costs. This includes provincial land transfer tax, legal fees, title insurance, home inspection costs, and appraisal fees. Buyers in the City of Toronto also face a municipal land transfer tax, though first-time buyers may qualify for a rebate on both the provincial and municipal amounts.
❓ What does mortgage pre-approval involve in Canada?
Pre-approval requires a formal review of your identification, proof of income, employment history, bank statements, existing debts, and confirmation of your down payment source. You must also pass the mortgage stress test. A strong pre-approval makes your offer competitive and prevents surprises after an accepted offer.
❓ What first-time buyer rebates are available in Ontario in 2026?
First-time buyers in Ontario may be eligible for the provincial Land Transfer Tax refund (up to $4,000), the Toronto Municipal Land Transfer Tax rebate (for Toronto purchases), and potentially HST/GST new-home rebates on qualifying new-construction purchases. Eligibility depends on purchase price, property type, and buyer status.
❓ Does Team Prestige serve buyers across the GTA?
Yes. Team Prestige — Harleen Singh & Priya Gill of Royal Canadian Realty — serve first-time buyers across Vaughan, Toronto, Brampton, Mississauga, Markham, and Southern Ontario including Peel Region, York Region, Durham Region, Waterloo Region, and the Hamilton-Burlington area. Call 647-492-6189 or visit teamprestige.ca to book a free consultation.
Whether you're just starting to research or ready to make a move, Team Prestige will walk you through your pre-approval, closing costs, rebate options, and whether the Zero Down Program could help you buy sooner — with confidence.
Monthly AwardsGold Club: August 2025 , December 2024 ,May 2024 ,August 2023....
🏆 Royal Premier Club Award 2025/2026 | 📞 647-492-6189 | www.teamprestige.caTeam PrestigeHarleen Singh & Priya Gill · Royal Canadian RealtyRoyal Premier Club
Team Prestige Priya Gill & Harleen Singh · Royal Canadian RealtyFree ConsultationGTA Real Estate Market Update 2026Market Analysis · June 2026GTA Real Estate Market Update 2026:
Royal Premier Club Award 2025 · Royal Canadian Realty · Believe In The Best™Brampton, Ontario · May 2026Best Commercial Investment Opportunities in
Royal Canadian Realty · Team Prestige | 647-492-6189 · 647-498-0186 · teamprestige.caTeam Prestige Harleen Singh & Priya&
 Toronto Real Estate Board (TRREB); All information deemed reliable but not guaranteed. All properties are subject to prior sale, change or withdrawal. Neither listing broker(s) or information provider(s) shall be responsible for any typographical errors, misinformation, misprints and shall be held totally harmless. Listing(s) information is provided for consumer's personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumers may be interested
in purchasing. The data relating to real estate for sale on this website comes in part from the Internet Data Exchange program of the Multiple Listing Service. Real estate listings held by brokerage firms other than Royal Canadian Realty, Brokerage, Mississauga may be marked with the Internet Data Exchange logo and detailed information about those properties will include the name of the listing broker(s) when required by the MLS. Copyright ©2026 All rights reserved.
Last Updated: September 22, 2026 7:07 PM UTC
Show More...

The listing data displayed is deemed reliable but is not guaranteed accurate by CREA®. Data last updated on September 22, 2026 8:59 PM UTC The trademarks REALTOR®, REALTORS®; and the REALTOR® logo are controlled by The Canadian Real Estate Association (CREA®) and identify real estate professionals who are members of CREA®. Used under license. The trademarks MLS®, Multiple Listing Service® and the associated logos are owned by The Canadian Real Estate Association (CREA®) and identify the quality of services provided by real estate professionals who are members of CREA®. Used under license.
Show More...
 Data provided by the Ontario Regional Technology & Information Systems. The information is deemed reliable, but is not guaranteed. Not intended to solicit buyers or sellers, landlords or tenants currently under contract.
The trademarks REALTOR®, REALTORS® and the REALTOR® logo are controlled by The Canadian Real Estate Association (CREA) and identify real estate professionals who are members of CREA. The trademarks MLS®, Multiple Listing Service® and the associated logos are owned
by CREA and identify the quality of services provided by real estate professionals who are members of CREA. Used under license.
REALTOR® contact information provided to facilitate inquiries from consumers interested in Real Estate services. Please do not contact the website owner with unsolicited commercial offers.
Show More...
